Insurance endorsements are where real risk transfer happens. Not the COI, not the limits, and not the ACORD form. If you’re a GC, risk manager, subcontractor or broker, endorsements decide whether you’re actually protected when a claim comes in.
This guide covers the three endorsements that matter most in construction:
- CG 20 10: additional insured for ongoing operations
- CG 20 37: additional insured for completed operations
- Primary and noncontributory (P&N)
For each one, you’ll see what it does, why GCs require it, the wording to look for and the most common gaps. We’ll also show how AI can review endorsements in seconds and how Billy automates the checks and the follow-up with subs.
What Is an Insurance Endorsement?
An insurance endorsement is an amendment to an insurance policy. It changes the contract between the insurer and the insured and spells out what the policy is allowed to cover.
On construction projects, endorsements decide:
- Who is an additional insured
- Which operations are covered
- Whose policy pays first in a claim
- Whether completed work is included
- Whether coverage applies to ongoing work
- Whether subrogation is waived
A COI can’t grant any of these rights. Only endorsements can. That’s why endorsement review is the most important part of compliance.
CG 20 10 vs. CG 20 37 vs. Primary and Noncontributory
| CG 20 10 | CG 20 37 | Primary & noncontributory | |
|---|---|---|---|
| What it does | Makes the GC an additional insured while the sub is working | Makes the GC an additional insured after the sub’s work is done | Makes the sub’s policy pay first, without contribution from the GC’s |
| When it applies | Ongoing operations | Completed operations | Any covered claim |
| Typical claims | Jobsite injuries, property damage during construction | Water intrusion, fire, defective installation, structural issues | Any claim where both policies could respond |
| Most common gap | GC not named, or blanket wording not triggered | Sub provides CG 20 10 but not CG 20 37 | Wording missing or buried in another form |
You need all three. CG 20 10 and CG 20 37 decide whether you’re covered and when. Primary and noncontributory decides whose policy pays first.
CG 20 10: Additional Insured (Ongoing Operations)
What it does
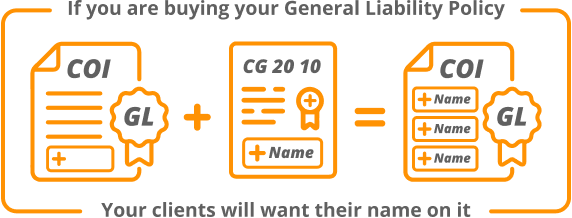
CG 20 10 gives additional insured status to the GC, owner or other upper-tier contractor while the subcontractor is still doing its work. If a claim comes up during construction, CG 20 10 protects the GC. Read the full CG 20 10 guide.
The edition matters
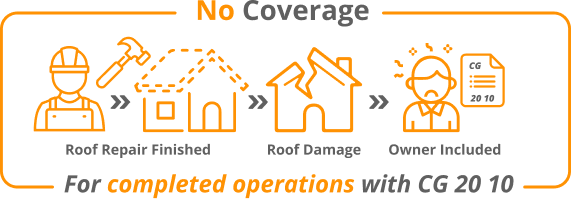
Older editions of CG 20 10, such as the widely used 11 85 form, covered both ongoing and completed operations. Editions from 10 01 onward cover ongoing operations only, which is why CG 20 37 now has to be required separately. Always check the edition date printed on the form.
Wording you should expect to see
- “Additional Insured: Owners, Lessees or Contractors, Scheduled Person or Organization”
- “With respect to ongoing operations”
- “Liability caused, in whole or in part, by your acts or omissions”
Common failure points
- Endorsement missing entirely
- GC not listed
- Coverage limited to premises only
- Only a blanket AI endorsement, when your contract requires a scheduled one
- Applies only if a written contract exists, but no contract is on file
CG 20 37: Additional Insured (Completed Operations)

What it does
CG 20 37 gives additional insured protection after the subcontractor’s work is finished. It matters because many of the costliest construction claims surface after a project is complete, especially:
- Water intrusion
- Fire
- Defective installation
- Structural issues
Wording you should expect to see
- “Additional Insured: Owners, Lessees or Contractors, Completed Operations”
- “‘Your work’ at the location designated”
- “Liability caused, in whole or in part, by your work”
Common failure points
- Sub provides CG 20 10 but not CG 20 37
- Policy has expired and no longer carries completed operations
- Completed operations coverage limited to zero years after completion
- Blanket endorsement excludes completed operations entirely
Primary and Noncontributory (P&N)
What it does
A primary and noncontributory endorsement makes sure that:
- The subcontractor’s policy responds first.
- The GC’s policy does not contribute unless the sub’s limits are exhausted.
Without P&N, the GC’s own policy can end up defending the claim first. Read the full primary and noncontributory guide.
Wording you should expect to see
- “This insurance is primary”
- “We will not seek contribution from any other insurance available to an additional insured”
Common failure points
- P&N endorsement missing
- P&N wording buried in another section, which many GCs won’t accept
- Endorsement only covers liability arising out of premises
- Applies only if required by contract, but no contract is on file
The Real-World Risk If These Endorsements Are Missing
If CG 20 10, CG 20 37 or P&N is missing, incomplete or expired:
- Claims can be denied
- GCs may have to tender to their own carriers
- Audits get expensive
- Brokers can’t defend coverage
- Projects face compliance delays
- Subcontractors may be barred from the site
That’s why endorsement review, not COI review, is what actually drives risk. Checking three endorsements across dozens of subs and projects by hand rarely holds up, which is where subcontractor compliance tracking tools earn their place. Don’t forget the fourth common requirement, waiver of subrogation (CG 24 04).
How Billy’s AI Analyzes Endorsements in Seconds
Billy’s AI is trained on thousands of endorsements, clauses from all major carriers, common compliance failures and GC contract requirements. When a subcontractor uploads a policy, Billy automatically:
- Detects whether CG 20 10 is present
- Detects whether CG 20 37 is present
- Confirms additional insured wording
- Extracts P&N language
- Flags missing required endorsements
- Summarizes key coverage limits
- Identifies blanket vs. scheduled AI
- Reads umbrella follow-form status
- Alerts project teams automatically
Billy then sends reminders to the sub until the correct endorsements come in. Review time drops from about 30 minutes per vendor to under 10 seconds.
Examples of AI outputs
Detected: CG 20 10 (ongoing operations)
Issue: GC not listed as additional insured
Action: Ask vendor for an updated blanket AI endorsement that includes the GC
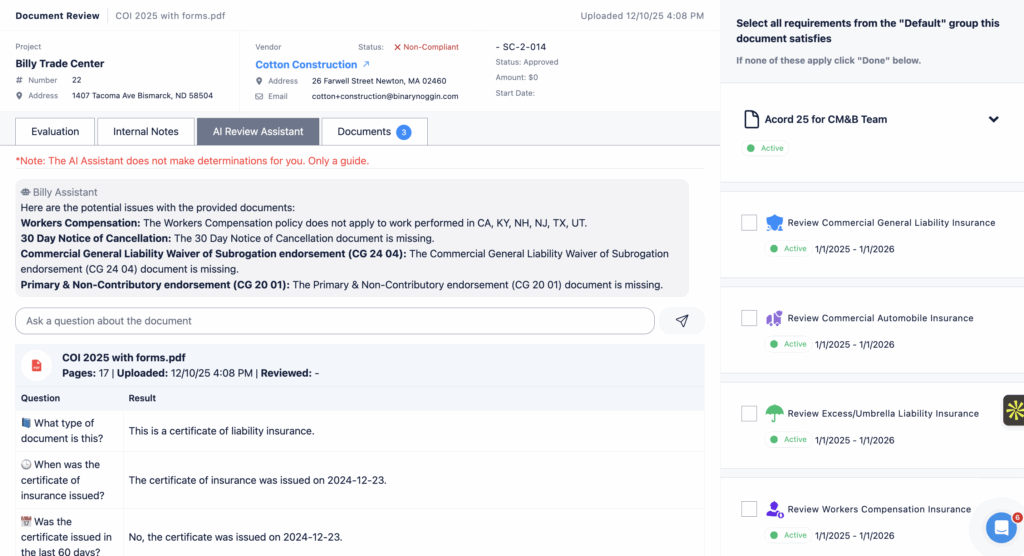
Detected: Missing CG 20 37 (completed operations)
Action: Request completed operations endorsement to keep post-project coverage
Detected: P&N wording not present
Action: Flag for risk manager review
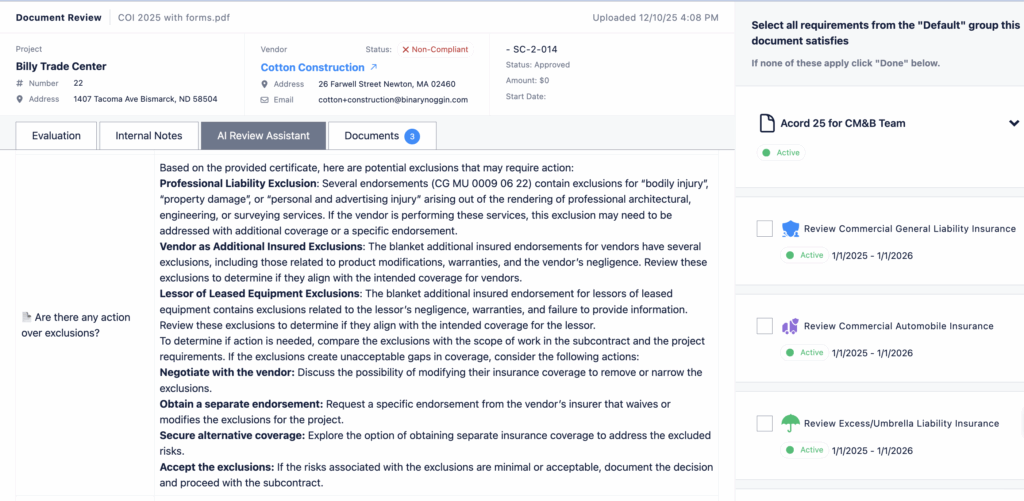
Billy’s AI Review Assistant
Instant COI and endorsement review that cuts out the back and forth. Vendors get guidance to fix their own mistakes, and your team gets fewer emails and corrections to chase.
Book a demoWhat GCs Should Require in Their Contracts
Minimum requirements
- CG 20 10 (ongoing operations)
- CG 20 37 (completed operations)
- Primary and noncontributory
- Waiver of subrogation
- Additional insured status for the GC and the owner
- Umbrella follow-form coverage
Sample contract language
Have your attorney or broker review contract language before you use it.
Common Subcontractor Pushbacks (and How to Respond)
“My carrier can’t issue CG 20 37.”
Most standard GL carriers can, often for a small fee or none. If a carrier truly won’t, ask for an equivalent completed operations endorsement and have your broker review it.
“The COI shows the GC is an additional insured.”
A COI can’t grant additional insured status. Only the endorsement does.
“We only provide blanket AI endorsements.”
Blanket is fine only if it clearly covers the GC and both ongoing and completed operations.
Why Billy Helps Reduce Claims and Audit Exposure
Billy makes sure you get the right endorsements up front, monitors policies for expiration, shows compliance status inside Procore, Autodesk, Sage and JD Edwards, and keeps a clean audit trail for carriers. Project admins spend far less time on manual review.
The result is fewer claim disputes, faster vendor onboarding, lower internal labor cost and a stronger risk position for the GC.
Endorsements Are the Heart of Risk Transfer
CG 20 10, CG 20 37 and primary and noncontributory endorsements decide whether your project is protected during construction and long after it’s finished. With AI-powered COI review, Billy makes endorsement verification faster, more accurate, standardized and audit-ready.
Frequently Asked Questions
What is the difference between CG 20 10 and CG 20 37?
CG 20 10 makes you an additional insured on the sub’s policy while their work is ongoing. CG 20 37 makes you an additional insured after their work is complete. Current editions of CG 20 10 don’t cover completed operations, so you need both.
Are CG 20 10 and CG 20 37 always issued together?
Not always. They’re separate ISO forms. Some carriers print them on one endorsement page and others issue them separately. Check that both are actually attached, not just referenced on the COI.
Do I need primary and noncontributory if I already have CG 20 10?
Yes. CG 20 10 makes you an additional insured, but it doesn’t decide which policy pays first. Without primary and noncontributory wording, your own policy may have to respond or share the loss.
Where can I get CG 20 10 and CG 20 37 forms?
The forms are copyrighted by ISO and issued by the subcontractor’s insurance carrier as part of their policy. Ask the sub’s broker for the actual endorsement pages attached to the policy, not a blank form.
Want your subcontractor endorsements reviewed automatically?
See how Billy checks CG 20 10, CG 20 37, P&N and waiver of subrogation on every document.
Schedule a demo